What PJM’s market monitor says data centers add to wholesale power costs
The monitor that polices PJM’s wholesale power market attributes 46.2 percent of the last four capacity auctions’ charges to data centers. How much of that reaches a household depends on the utility; Pennsylvania’s June 1 rate changes and price changes in 50 states and D.C. show a mixed picture.
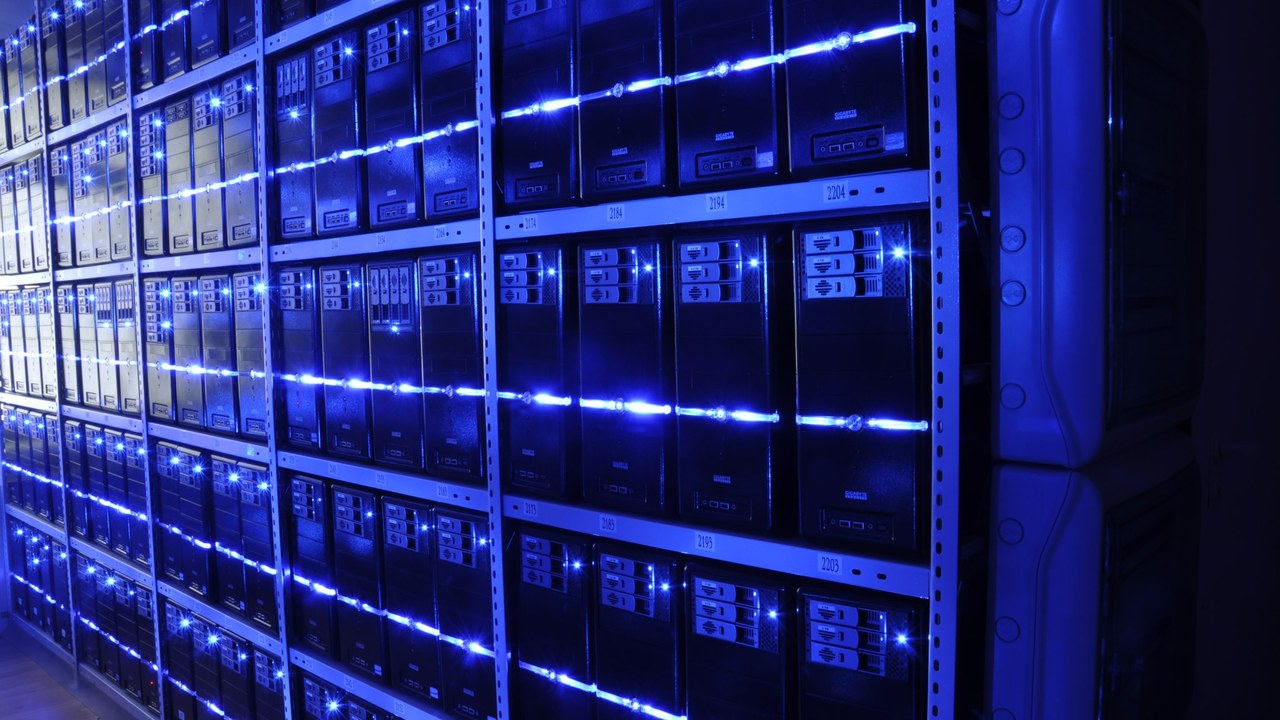
Credit: BalticServers.com, CC BY-SA 3.0, via Wikimedia Commons
What the market monitor found
Start with the market most of the East Coast lives inside. PJM Interconnection runs the wholesale power market for all or parts of thirteen states and the District of Columbia, Virginia and Maryland and Pennsylvania and Ohio and New Jersey among them. PJM has an independent referee called Monitoring Analytics. The table sets three of its snapshots side by side, because they cover different months and are easy to confuse. The newest is its September 28 presentation, which runs through August.
| Measure | January to June 2026, from the monitor’s July 27 presentation | January to July 2026, as Utility Dive reported on August 27 | January to August 2026, from the monitor’s September 28 presentation (newest) |
|---|---|---|---|
| Total wholesale cost per megawatt-hour | $114.50, up 50.3% from $76.16 a year earlier | $116.53, up 46%, or $56.7 billion | $112.51, up 42.5% from $78.98; $63.57 billion, up 46.3% |
| Attributed to data-center load | $11.11 per megawatt-hour, 9.7%; the monitor says the total would have been $103.40 without it | $10.48 per megawatt-hour, 9%, for “existing and forecast” data-center load | $10.10 per megawatt-hour, which the slide gives as 9.0%; the monitor says the total would have been $102.41 without it |
| Data-center estimate as a share of the capacity component (our calculation) | 56.7% (11.11 of $19.61) | Not given in the report | 52.4% (10.10 of $19.27) |
| Data-center estimate as a share of the total increase (our calculation) | 29.0% (11.11 of $38.34) | 28.4% (10.48 of $36.96) | 30.1% (10.10 of $33.53) |
| What it leaves out | Not all of the increase in capacity costs came from data centers, the monitor says | Comes through the capacity market only; Utility Dive says it does not include data-center-related increases in electricity or transmission prices | Not all of the increase in capacity costs came from data centers, the monitor says; the estimate covers the 2025/2026 and 2026/2027 delivery years |
| Component | January to June 2025 | January to June 2026 | Increase | Share of the $38.34 increase |
|---|---|---|---|---|
| Energy | $49.21 | $72.68 | $23.47 | 61.2% |
| Capacity | $6.39 | $19.61 | $13.22 | 34.5% |
| Transmission | $18.82 | $19.88 | $1.06 | 2.8% |
| Ancillary services | $1.06 | $1.63 | $0.57 | 1.5% |
| Administration | $0.67 | $0.69 | $0.02 | 0.1% |
| Total | $76.16 | $114.50 | $38.34 | 100% |
| Component | January to August 2025 | January to August 2026 | Increase | Share of the $33.53 increase |
|---|---|---|---|---|
| Energy | $49.58 | $71.90 | $22.32 | 66.6% |
| Capacity | $9.55 | $19.27 | $9.72 | 29.0% |
| Transmission | $18.17 | $19.13 | $0.96 | 2.9% |
| Ancillary services | $1.01 | $1.54 | $0.53 | 1.6% |
| Administration | $0.65 | $0.67 | $0.02 | 0.1% |
| Total | $78.98 | $112.51 | $33.53 | 100% |
The first table’s components come from the monitor’s July 27 presentation (slides 10 and 11) and the second’s from its September 28 presentation; the shares are our calculation, and components may not add exactly to the total because the monitor rounds each line (the January-to-August increases add to $33.55 against $33.53). Energy, not capacity, supplied most of the increase in both periods. Set the data-center estimate beside the capacity component and the total increase and the ratios hold steady: $11.11 is 56.7 percent of the $19.61 January-to-June capacity component and $10.10 is 52.4 percent of the $19.27 January-to-August one, and the estimate is 29.0 percent of the $38.34 total increase in the first period and 30.1 percent of the $33.53 increase in the second (each divides the estimate by the figure named). A ratio against the capacity increase is left out because it swings with the month, 84.0 percent on the January-to-June figures and 103.9 percent on the January-to-August ones. The estimate is a level, what data-center load adds to the period’s price, and the increase is a year-over-year change, so none of these shares says data centers caused that part of the increase. Even on the monitor’s own figures, data-center load is a large part of the capacity story and a smaller part of the whole wholesale increase. One reading note: the September slide calls the $10.10 “9.0 percent”; that is its share of the $112.51 total (8.98), and measured against the $102.41 without data centers it would be 9.9 percent.
The sharper number is in the capacity market. Capacity is the insurance the grid buys years ahead so the lights hold on a hot Tuesday in July. PJM auctions it. The 2026/2027 auction, for the delivery year that began on June 1, 2026 (per the Citizens Utility Board), cleared at $329.17 per megawatt-day, the ceiling the auction is allowed to reach, 11.4 times the $28.92 of the 2024/2025 auction (329.17 divided by 28.92; our calculation). Monitoring Analytics attributed $29.4 billion of the capacity charges across the last four auctions, 46.2 percent of the total, to data center load. For the most recent auction, 2028/2029, it attributed $6.3 billion of $16.4 billion in capacity charges and reports 38.2 percent; the rounded dollars give 38.4 percent. PJM’s own July 14, 2026 release says that auction cleared at the $325 per megawatt-day cap for the whole footprint, procured 138,318 megawatts and fell 6,831 megawatts short of the reliability requirement. It also defines the $16.4 billion: “The cleared supply procured in the auction times the clearing price totals $16.4 billion” (325 x 138,318 x 365 = $16,407,972,750, our check), and it adds that “the total value does not equate to the total cost to load because load that is hedged through self-supply or bilateral contracts is not exposed to the clearing prices.” That total is not what customers paid. The figures above are the monitor’s with-and-without comparisons of what the auctions would have cost, not a count of dollars moved from one household to another. In the January-through-June comparison, the capacity component of wholesale cost rose from $6.39 to $19.61 per megawatt-hour, which is 3.07 times the $6.39 of a year earlier (19.61 divided by 6.39; our calculation).
How much of that reaches a household is a separate question, and PJM has answered part of it. When the 2026/2027 auction cleared, PJM wrote that “wholesale capacity accounts for a relatively small portion of retail electricity bills,” and that it expected the cap price to mean “a year-over-year increase of 1.5–5% in some customers’ bills, depending on how load serving entities and states pass on wholesale costs to consumers.” That estimate is for the capacity price as a whole, not for the share the monitor assigns to data centers.
One PJM state has measured retail changes for the same delivery year. On May 20, 2026 the Pennsylvania Public Utility Commission listed the changes in the default-service “Price to Compare” that took effect on June 1, 2026, the first day of the 2026/2027 delivery year, for 11 utilities. They run from +0.05% to +19.8%, and the median is +6.9% (the sixth of the 11 in order).
| Utility | Change |
|---|---|
| Citizens’ Electric | +0.05% |
| PPL | +1.5% |
| Wellsboro Electric | +1.65% |
| Duquesne Light | +2.84% |
| PECO | +4.97% |
| Penn Power | +6.9% |
| Met-Ed | +7.6% |
| West Penn Power | +10.3% |
| Penelec | +11.88% |
| UGI Electric | +12.53% |
| Pike County Light & Power | +19.8% |
The comparison has three limits. The Price to Compare is the generation price only, which the Commission says “may account for roughly 50% or more of a total electric bill,” so at a 50% share the median 6.9% generation change would be about 3.5% of a total bill (6.9 x 0.5 = 3.45), inside PJM’s range. It applies only to customers on default service, not to those who chose a supplier. And it mixes energy, capacity and other supply costs, so it cannot say how much of any change comes from data centers. It is still the only measured retail change in this part, and it shows generation prices moving by very different amounts across one state’s utilities.
Where it lands on your statement
| State or group | August 2026 | August 2025 | Change |
|---|---|---|---|
| District of Columbia | 25.98 | 23.18 | +12.1% |
| Virginia | 17.64 | 15.85 | +11.3% |
| Delaware | 18.70 | 16.85 | +11.0% |
| Ohio | 19.38 | 17.55 | +10.4% |
| Pennsylvania | 21.77 | 19.93 | +9.2% |
| Maryland | 21.40 | 19.89 | +7.6% |
| West Virginia | 16.31 | 15.62 | +4.4% |
| New Jersey | 24.61 | 24.70 | -0.4% |
| Eight places wholly or mostly in PJM | median +9.8%, mean +8.2% | ||
| Six states partly in PJM (IL, IN, KY, MI, NC, TN) | median +5.2%, mean +5.6% | ||
| 37 states outside PJM | median +4.6%, mean +4.4%; 31 of 37 rose | ||
| U.S. average | 18.16 | 17.57 | +3.4% |
Seven of the eight places that are wholly or mostly in PJM paid more in August 2026 than a year earlier, and the median was +9.8%. Virginia went from 15.85 cents a kilowatt-hour to 17.64, Maryland from 19.89 to 21.40 and Ohio from 17.55 to 19.38. New Jersey, also in PJM, went the other way, down 0.4 percent. Outside PJM the median change was +4.6% and 31 of 37 states rose. Nine of the 37 rose by more than Maryland’s 7.6%: Hawaii (+22.5%, from 38.53 cents to 47.18), Maine (+14.1%), New Hampshire (+13.1%), Idaho (+10.7%), Iowa (+10.2%), South Dakota (+9.0%), Montana (+9.0%), Vermont (+7.9%) and Arkansas (+7.8%). Michigan, which PJM serves in part, rose 10.9%. Florida, outside PJM, fell 2.2 percent, to 14.99 cents from 15.33.
So the PJM states rose faster on average, and prices rose in most of the country. The table cannot say why. A state’s average price mixes fuel costs, delivery charges, rate cases and weather, and this one covers a single month, so it does not isolate data centers. Treat it as the retail side of the picture, to set beside the wholesale numbers above, and not as proof that data centers raised any particular bill.
The wall the regulators are building
Regulators heard the same alarm and started building walls. In Virginia the State Corporation Commission approved a new rate class, GS-5, for customers with 25 megawatts or greater of demand and a load factor of at least 75 percent. Its November 25, 2025 order takes effect on January 1, 2027, and it is written to keep a campus from vanishing and leaving households holding a substation. The terms are the interesting part: a 14-year contract and minimum charges set against contracted demand, whether the customer uses the power or not. The same order (page 26) approves Dominion’s proposal to “exclude PJM capacity expense from the minimum generation demand charge,” so the capacity costs this part is about sit outside that minimum as the order words it. Part 6 has every term with its order page.
Georgia Power, ComEd and Oncor have written their own versions. The energy consultancy E3, in a May 2026 white paper, priced a hypothetical 25-megawatt data center under five tariffs. Its row labeled “Annual Bill (¢/kWh-yr)” is an effective rate per kilowatt-hour over a year, not a dollar bill, and it runs from 5.44 cents under Oncor to 9.43 under Georgia Power, 3.99 cents apart, with Dominion’s GS-5 at 7.96. Oncor’s own row lists an average energy charge of 6.67 cents, above its 5.44, and E3 does not explain the gap; it says only that in deregulated markets “lower utility charges may be offset by greater exposure to wholesale price volatility.” That is a modeled comparison for one hypothetical customer, and Part 9 shows all five.
The Data Center Coalition, the industry’s trade group, funded a second E3 report in May 2026, “Understanding the Drivers of Rising Electricity Rates and the Role of Data Centers,” and its case belongs here. The report states that the Coalition reviewed it before publication and that the conclusions are E3’s own. It says data centers have become “an easy focal point” in discussions of rising costs while the evidence points to a more complex picture, and it counts at least 38 new large-load tariffs established since 2018, 30 of them in 2025 and 2026. A tariff like GS-5 exists so that the new customer, not the neighbor, carries the cost of the wire. Inside commissions, the fight now is over who signs for the wire, and whether the signature holds up if a tenant cancels.
The national picture
At the national level, Goldman Sachs analysts forecast in a February note to clients that consumer electricity inflation would jump 6 percent from 2026 to 2027 before slowing to 3 percent the following year, owing to lower natural gas prices, according to Fortune. Fortune does not give a reason for the 6 percent jump in that sentence; elsewhere it ties rising bills to data centers, an aging grid, extreme weather and gas prices. We have not opened the Goldman note. Treat the figure as a forecast for the whole country, not a meter reading and not a data-center number.
Update, October 29, 2026: The headline, opening and state table now say the monitor measures wholesale charges, and the table of four states was replaced by all states grouped by PJM membership. Earlier corrections: the GS-5 description (separate floors for distribution, transmission and generation, September 24); the seven-month wholesale figures, now from Utility Dive’s report on the monitor’s later numbers with the six-month figures beside them (October 24); the auction price as 11.4 times the 2024/2025 price; “more than tripled” replaced by the monitor’s January-through-June figures; E3’s range corrected from 6.4 to 9.4 cents to 5.44 to 9.43; the pass-through wording and the Goldman clause about AI demand removed. Added: the page-26 carve-out of PJM capacity expense from the GS-5 minimum generation charge, a comparison of the monitor’s two snapshots and a breakdown of where the increase came from. Cut: the closing line and a photo caption that claimed more than the photo shows. Added in a later pass: the 2028/2029 auction with PJM’s statement that its $16.4 billion is not the total cost to load, Pennsylvania’s June 1 price changes set against PJM’s 1.5 to 5% range, Hawaii in the outside-PJM list, and a note on what the 84 percent compares. Revised later on October 29: the monitor’s September 28 presentation (January through August) is now the newest snapshot, with a third column and its own component table; the 84 percent ratio was dropped because it changes with the period it is computed on (the same division on the September figures gives 103.9), and the data-center estimate’s share of capacity cost and of the total increase replaced it; the Maryland list now names all nine outside-PJM states that rose by more, where Arkansas, Montana, South Dakota and Vermont had been missing, and notes Michigan; the 2024/2025 auction price now links to PJM’s report at the figure; and the title no longer promises a household bill.
- Monitoring Analytics (PJM’s independent market monitor): about 9 percent of wholesale costs ($10.48/MWh) attributed to data centers through July 2026; wholesale costs $56.7 billion, up 46 percent; $29.4 billion (46.2 percent) of capacity charges across the last four auctions attributed to data centers; position that the load belongs in a dedicated auction. Utility Dive; PJM market-monitor presentation, July 27, 2026 (January through June: 9.7 percent, $11.11/MWh, and the four-auction estimate); PJM market-monitor presentation, September 28, 2026 (January through August: $112.51/MWh total and the $10.10/MWh data-center effect).
- PJM 2026/2027 Base Residual Auction cleared at $329.17 per megawatt-day, the FERC-approved cap, with PJM’s estimate of the effect on retail bills: PJM Inside Lines. Delivery year June 1, 2026 to May 31, 2027: Citizens Utility Board. 2024/2025 price: PJM auction report.
- PJM 2028/2029 Base Residual Auction results and the definition of the $16.4 billion: PJM Inside Lines, July 14, 2026. Pennsylvania default-service price changes effective June 1, 2026: Pennsylvania Public Utility Commission, May 20, 2026.
- Average residential electricity price by state, August 2026 vs. August 2025: U.S. Energy Information Administration, Electric Power Monthly, Table 5.6.A (as retrieved October 29, 2026; the file updates monthly).
- Virginia State Corporation Commission, final order, Case No. PUR-2025-00058, November 25, 2025 (GS-5 class, effective January 1, 2027; the terms with page numbers are in Part 6).
- E3 (Energy and Environmental Economics), large-load tariff white paper, May 2026 (Table 4); E3, Understanding the Drivers of Rising Electricity Rates and the Role of Data Centers, May 2026 (funded by the Data Center Coalition).
- Goldman Sachs Research, “The Macroeconomic Spillovers From AI Electricity Demand,” February 11, 2026 (consumer electricity inflation forecast; the note itself was not opened). Reporting via Fortune.
- Illinois Citizens Utility Board on the 2026/2027 auction, July 22, 2025. CUB.
Editor written. AI used for spelling and grammar only.