Florida paid to study the fees insurers pay their sister companies. The Senate’s lawyer told two newspapers to shred it.
A consultant the state hired found that for many Florida-based insurers, companies with the same owners were making money on fees while the insurer itself reported a loss. Two newspapers published the company names this month after the Senate's top lawyer demanded they destroy the report.
 Todd Ruffner-Schoenfeld
Editor in chief. A knack for the fine print, and likes it.
If you own a home in Florida, you have spent most of this decade hearing that the companies insuring it were losing money. Rates climbed and several insurers failed. In 2022 the Legislature met twice in special session to change the rules for suing an insurer, changes the governor’s office said would help stabilize the market.
During those same years, the state’s insurance regulator paid a Connecticut consulting firm about $150,000 to look at something most homeowners never see. Many Florida insurers belong to a family of companies owned by the same people. Some of those sister companies take a share of every premium as a fee for running the insurer’s business. The consultant’s report, dated March 2022, found that for many Florida-based insurers the sister companies were making money on those fees while the insurer itself reported a loss.
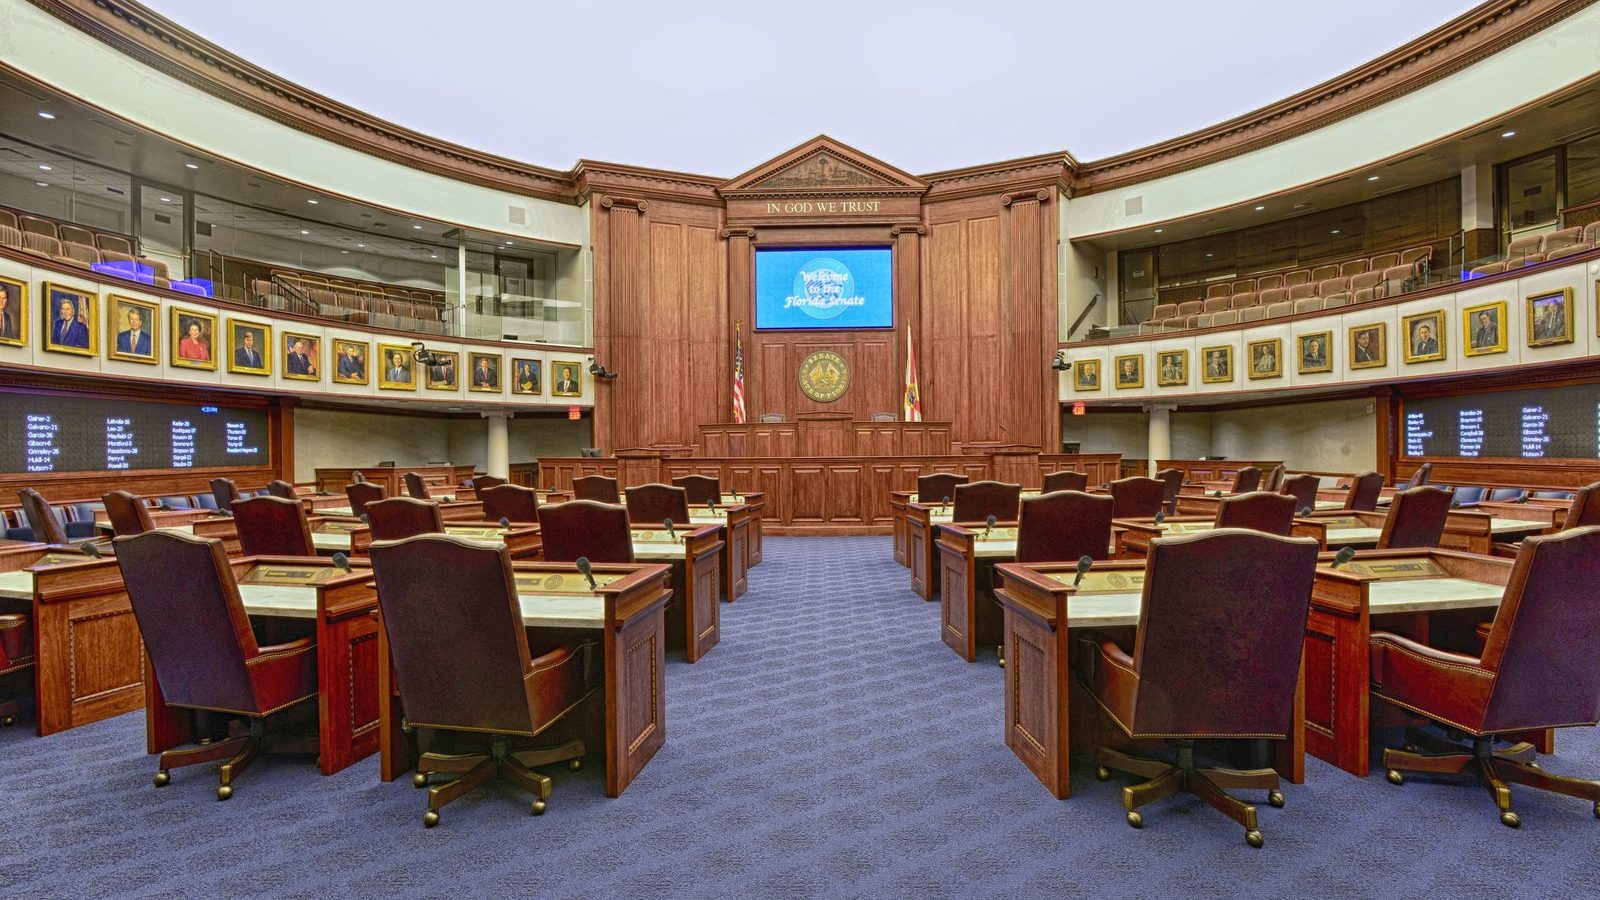
The regulator did not give the report to lawmakers before they voted on the 2022 changes, the Miami Herald and Tampa Bay Times later reported. A short summary came out last year, but the company-by-company detail stayed out of public view until this month. In July, the Orlando Sentinel and the South Florida Sun Sentinel received the full report, with nothing blacked out, from the Florida Senate itself, in response to a public records request. Once the state learned the papers had it, the Senate’s top lawyer demanded they destroy every copy and warned of criminal consequences. They published on September 19.
How an insurance family is set up
The name on the first page of your policy, the declarations page, is the insurance company. Behind it, the insurer’s owners often run other businesses, called affiliates or sister companies, that do the insurer’s work and bill it for the service. The insurer pays those fees as expenses before it adds up its own profit or loss. That is how an insurer can report a loss in the same years its owners’ other companies make money.
| Company in the family | What it does | How it gets paid |
|---|---|---|
| The insurance company | Issues your policy, keeps money set aside to pay claims, files rates and faces state exams | Your premium comes in; claims and fees go out |
| Managing general agent | Runs the insurer’s daily operations, often including deciding whom to insure and handling billing | A share of premium, 20 to 34 percent on the agreements the consultant reviewed |
| Claims company | Handles and adjusts claims | A fee per claim or another share of premium |
| Sister agency | Sells the group’s policies | A commission |
| Investment manager | Invests the insurer’s money | A fee billed to the insurer |
| Holding company | Owns all of the above | Dividends, profits paid out by the companies it owns |
Setting up a family like this is legal, and it is common in Florida. Large national insurers typically handle all of that work inside the company, according to the Herald and Times. Florida-based carriers often buy it from a sister company instead. The fees to the managing general agent and the claims company are separate from the commission an independent agent earns for selling you a policy.
The managing general agent is usually paid a percentage of each premium. That means the sister company’s take grows every time the rate goes up, even when it is doing the same work. Say, to use made-up numbers, a sister company takes 25 percent of a $5,000 premium. It collects $1,250. If the state approves a 20 percent increase, the premium becomes $6,000 and the sister company’s share becomes $1,500, a $250 raise for the same policy. Florida’s rate law has the regulator weigh the insurer’s expenses, which include the fee. The sister company’s profit is not on the list of things the regulator must consider.
When the insurer and the company it pays have the same owners, nobody on the other side of the deal has a reason to push the fee down. Florida has a rule that says the terms of deals inside an insurance family must be “fair and reasonable” and the fees “reasonable,” without saying what that means in dollars.
What the state’s study found
The Office of Insurance Regulation hired Risk & Regulatory Consulting to do the study in 2020 and 2021. The firm’s executive summary, written by consultant Jan Moenck and dated March 31, 2022, covers 53 insurers. Thirty-five work only in Florida or in a few states, and 18 are national companies. For each one, the consultant compared the insurer’s profit or loss from 2017 through 2019 with what its affiliates earned from serving it.
With no dollar standard in the rule, the firm set its own cutoff by comparing what the sister companies made with what the insurer made. Where the sister companies came out far enough ahead, it marked the arrangement “not fair and reasonable.” Nineteen of the 35 Florida-based and regional insurers were marked that way. So was one of the 18 national companies. The firm could not reach a verdict on 11 of the national companies and five of the others, because it did not have complete information.
By the count of the two Sentinels, which leaves out a few companies whose results were far out of line with the rest, the insurers studied lost about $432 million from 2017 to 2019 while their affiliates made about $1.3 billion in profit. For one insurer, all the affiliated fees together reached 63 percent of premium. Coverage of the summary last year also cited a much bigger number, about $14 billion in affiliate profit. That total counted every company in the study, including two national insurers whose affiliates made far more than everyone else’s.
Insurers named in the report
The Sentinel newspapers named Heritage Property & Casualty Insurance Co., based in Clearwater, and Universal Property & Casualty Insurance Co., based in Fort Lauderdale, among the insurers whose affiliate fees the consultant flagged. According to the two Sentinels, Heritage reported nearly $81 million in losses over those three years while its affiliates generated $174 million in profit. Heritage did not respond to the papers’ request for comment. The company has since announced two state-approved rate cuts for its Florida homeowners, each averaging 3.3 percent: one in 2024 and one that took effect in February 2026.
Universal’s figures come combined with a sister insurer, American Platinum Property and Casualty: a loss of $11.1 million across the two, and about $166 million in profit for an affiliate. Travis Miller, a Universal spokesman, said the losses “must be viewed in the context of Hurricane Irma and the significant claims activity that followed.” He said the parent company later put nearly $400 million into its insurers, “substantially exceeding the $166 million mentioned,” and that the insurers have filed their third straight annual rate decrease.
Moenck told lawmakers she did not judge whether the fees contributed to any company’s failure. Three of the flagged insurers failed, the papers reported: Gulfstream Property and Casualty, Avatar Property & Casualty and FedNat Insurance. All three went under in 2021 and 2022. FedNat and a subsidiary lost $42 million over the three years, and their affiliates made at least $79.4 million. A court in Leon County ordered FedNat into liquidation in September 2022.
Limits of the study
The study covers 2017 through 2019, the years Hurricane Irma and Hurricane Michael hit Florida. Moenck testified before a Florida House subcommittee in April 2025. She said she had not weighed whether the fees raised premiums, and when asked whether she had found insurers breaking state regulations, she said no. The regulator has said the work was an internal analysis and “not a formal examination report.” Insurance Commissioner Michael Yaworsky has gone further, calling it an unfinished draft with “a great deal of errors, inconsistencies, data validation issues and antiquated information.” Moenck told the subcommittee the report was substantially complete. Her firm labels reports as drafts until the client reviews them, she said, and the regulator never answered its requests for a final review. Yaworsky’s office declined to tell the Sentinel newspapers what the errors were, saying that would require disclosing protected data.
Some money flowed the other way. Reading the executive summary in 2025, the Herald and Times reported that the affiliates of Florida-based insurers waived $208 million in fees during the study years and put $485 million back into the insurers.
The Senate’s demand to destroy the report
The summary the Herald and Times published in February 2025 left out the company-by-company detail, and the House held hearings on it. When the two Sentinels asked the Senate this April for legislative emails, the copy the regulator had emailed to a Senate staffer came back attached to one of them.
On Monday, September 14, the papers told the regulator they had the full report. The next day Tom Thomas, the Senate’s general counsel, emailed Sun Sentinel reporter David Fleshler under the heading “mandatory demand for compliance,” according to the U.S. Press Freedom Tracker, which logs incidents involving journalists. He told the newspapers to stop using the documents, delete the electronic copies, shred the paper ones, tell anyone else who had them to destroy theirs, and certify the destruction within 48 hours. He wrote that the records contain “sensitive, proprietary trade secrets,” that failing to comply “may result in civil or criminal legal implications,” and that the Senate had released them through an “inadvertent administrative oversight.” The papers reported that the letter also said any further use would be a third-degree felony, a crime punishable in Florida by up to five years in prison.
The two papers’ editors, Gretchen Day-Bryant of the Sun Sentinel and Roger Simmons of the Orlando Sentinel, declined to comply, and the story ran four days later. No arrest, charge or court order had been reported as of Wednesday night. Ken Paulson, who directs the Free Speech Center at Middle Tennessee State University, told the papers that once a government body releases information in answer to a lawful public request, the “cat is literally out of the bag.” Barbara Petersen, president of the Florida Center for Government Accountability, said of the Senate’s demand, “It is an attempt to chill and intimidate.”
State Sen. Carlos Guillermo Smith, an Orlando Democrat, questioned his own chamber’s demand. “Who are we trying to protect here,” he said, “the giant property insurance companies, or ratepayers and our constituents?”
A House bill to count affiliate profits
In February the Florida House passed House Bill 1399, 106 to 3. It would have required the regulator to count an insurer’s affiliates’ profits when reviewing that insurer’s rates. It would also have let the regulator treat a rate as excessive if the filing left those profits out, made affiliates register with the state, and made insurers document why each payment to a sister company was fair and reasonable. The bill went to the Senate Rules Committee, which decides what reaches the full Senate, and died there on March 13 without a vote.
The regulator has stressed that it gained more oversight of managing general agents and affiliate fees in 2022 and has since canceled or modified a number of those agreements. Yaworsky has pushed the Legislature, which has not acted, to spell out what “fair and reasonable” means.
At your next renewal
Your insurer’s contracts with its sister companies are private. When your renewal comes in higher, ask your agent whether the company uses an affiliated managing general agent and what share of the premium that agreement takes. If the fee is a flat share, that same share of your increase goes to the sister company.
The two Sentinels say this story is part of a yearlong investigation, and the series built from it, which they are calling “Uncovered,” begins in the coming weeks. Lawmakers return for their next regular session on March 2, 2027, and a bill on affiliate profits would have to be filed again to be considered. Any legislator can file one.
- Orlando Sentinel and South Florida Sun Sentinel, “How Florida fights to hide insurers’ finances,” by Skyler Swisher, Ron Hurtibise and David Fleshler, September 19, 2026. Source of the unredacted-report figures, the named insurers, the Senate letter and the Paulson and Smith quotes. Orlando Sentinel via Yahoo News.
- Risk & Regulatory Consulting, “Affiliated Fee Analysis Executive Summary,” March 31, 2022, from Jan Moenck to the Florida Office of Insurance Regulation. DocumentCloud.
- Miami Herald and Tampa Bay Times reporting on the executive summary, February 22, 2025. Tampa Bay Times.
- Insurance Journal, account of Jan Moenck’s testimony to the Florida House Insurance & Banking Subcommittee, April 4, 2025. Insurance Journal.
- U.S. Press Freedom Tracker, entry on the Florida Senate general counsel’s September 15, 2026 email to the Sun Sentinel. U.S. Press Freedom Tracker.
- Florida Legislature, House Bill 1399 (2026), “Property Insurance Affiliates”: bill history and House staff analysis. Florida Senate.
- Florida Administrative Code Rule 69O-143.047, standards for transactions between insurers and affiliates. Legal Information Institute.
- Florida Statutes 627.062, rate standards, and 775.082, penalties for a third-degree felony. Online Sunshine.
- Heritage Insurance Holdings, announcements of approved Florida homeowners rate decreases, May 22, 2024 and December 4, 2025. Heritage Insurance.
- Florida Department of Financial Services, Division of Rehabilitation and Liquidation, FedNat Insurance Company receivership record. Florida DFS.
- Office of Insurance Regulation statement on managing general agent oversight since 2022, as reported by Realtor.com via SFGate. SFGate.
- The Florida Bar News on the December 2022 special session property insurance package. The Florida Bar.
- Florida Senate, 2027 session dates. Florida Senate.