Amendment 3 would cut your Florida property tax. Nothing in it limits your water bill or your insurance premium.
Florida's DOGE combed city budgets to build the case for Amendment 3. Nothing in the amendment limits what your city can charge for water, and a bill to make regulators count what insurers pay their own sister companies died in the Senate.
 Todd Ruffner-Schoenfeld
Editor in chief. A knack for the fine print, and likes it.
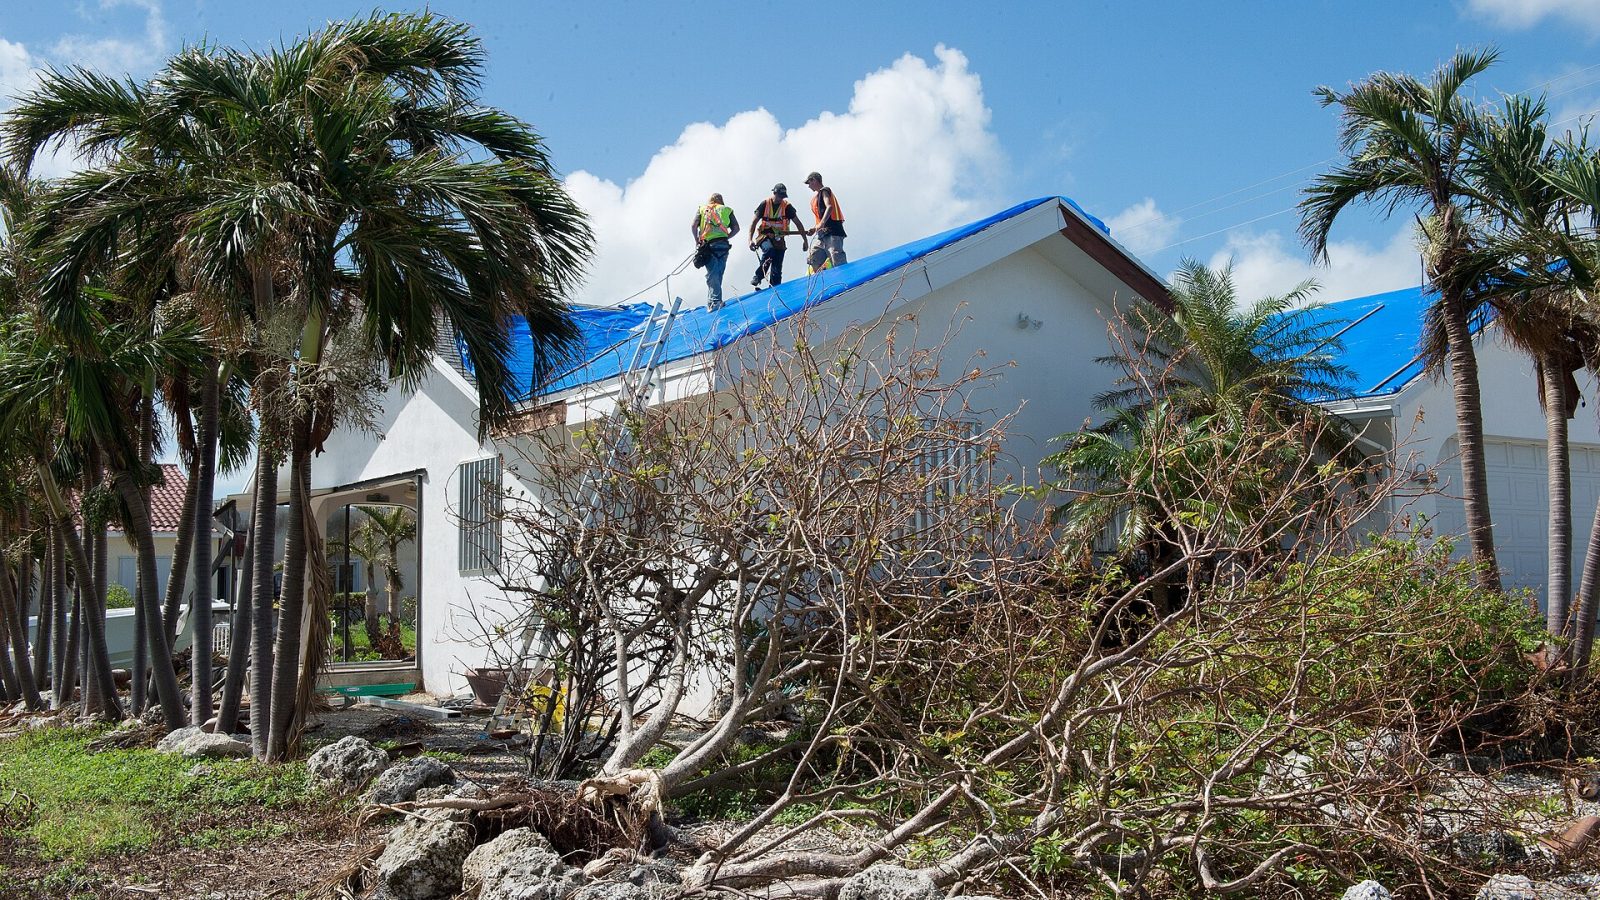
Credit: Photo: J.T. Blatty, FEMA, public domain, via Wikimedia Commons. · Public domain (U.S. federal government work)
On Oct. 1, 2025, Gov. Ron DeSantis and Florida’s chief financial officer, Blaise Ingoglia, whose office runs the local-government reviews for the state’s new Department of Government Efficiency, or DOGE, held a news conference at Jacksonville International Airport to point to what they called local government waste: a hologram of Mayor Donna Deegan that greeted travelers in several languages. The city had paid about $75,000 for it, counting the decorative cover on the machine, the installation and the video shoot, and the money came out of a city fund built from building-permit fees and meant for permit work. Ingoglia called it “$75,000 of waste, fraud and abuse.” Deegan stood by it as a new way to welcome visitors. The machine came down in February, when its six-month trial ran out, and she said the airport had been put through “constant hyper-partisan attacks.”
The next day, Ingoglia was in Orlando, pointing to a $6,000-a-year city poet laureate and, by his office’s count, nearly $70,000 spent on hot yoga classes for city employees. Mayor Buddy Dyer said the city had not raised its property tax rate in more than 10 years and called the tour “kind of a show that they’re going around.”
Ingoglia told Axios that month what the tour was for: “All of this is laying a predicate to reducing property taxes.” DeSantis created DOGE by executive order in February 2025 to review spending by state agencies, universities, counties and cities. Its report in January 2026 listed more than $1.86 billion in spending it labeled wasteful across Florida’s biggest cities and counties, though it did not accuse anyone of a crime. Ingoglia has acknowledged that much of what his team calls waste is “subjective,” according to Axios.
The property tax cut the tour was building toward is now on your Nov. 3 ballot as Amendment 3. I am not going to tell you how to vote on it. Amendment 3 would lower your property tax bill. It does nothing to limit two other bills the same homeowner pays: the fees and utility rates a city charges its residents, and the homeowners insurance premium, part of which goes to companies owned by the same people as the insurer. If the state is going to go through city budgets line by line to show homeowners how their tax money is spent, it should look just as hard at those.
What Amendment 3 does
An exemption is the part of your home’s value that is not taxed. For a home you live in and claim as your homestead, Amendment 3 raises that exemption for the part of the tax that does not go to schools, from $50,000 today to $150,000 in 2027 and $250,000 in 2028, and then lets it rise with inflation. School taxes do not change. The yearly limit on how fast the taxed value of rentals, second homes and businesses can rise drops from 10 percent to 5 percent. The tax money counties and cities still collect must go to a list of “core public needs,” such as police, fire, roads and debt. Anyone who buys a Florida homestead after Dec. 31, 2026, waits five years before getting the larger exemption. The amendment needs 60 percent of the vote to pass.
My husband Ron and I own a house in Clermont. Leaving out school taxes, we pay Lake County, the city and the regional water management district about $9.79 for every $1,000 of the home’s taxed value. Exempting another $200,000 of value saves us roughly $1,960 a year starting in 2028, as I figured in August. Our five-part guide to Amendment 3 goes through the rest, including what it does to county budgets.
Supporters say local governments have had years of rising tax collections and should cut their own spending before they ask more of homeowners, which is the case DeSantis has made for the measure. Opponents, including many county officials, say the cut will be paid for with fewer services or higher fees. “This is not a tax decrease; it’s simply a tax shift,” said Joe Abruzzo, the Palm Beach County administrator.
Amendment 3 does help elderly, retired homeowners, and I believe they deserve a bigger exemption than this one, possibly no property tax at all on the home they live in. Florida law already lets counties and cities give some seniors more. A local government can give homeowners 65 and older with low household incomes, $38,686 or less for 2026, an extra exemption of up to $50,000. It can also exempt the entire value of a home worth less than $250,000 for seniors under the same income limit who have lived there at least 25 years. Each one lowers only the tax of the county or city that grants it. Both take a vote of the county commission or city council, and seniors have to file a sworn statement of their income with the property appraiser by March 1. Part 4 of our guide looks at who Amendment 3 helps most.
What stops a city from raising your water bill instead
Amendment 3 limits property taxes. It says nothing about fees, and it does not stop a county or city from raising its tax rate, the Florida Policy Institute, a budget research group, notes in its guide to the measure. Part 2 of our Amendment 3 guide went through the charges local governments already use, from fire assessments to stormwater fees.
Take my own city. Clermont runs its own water and sewer utility, and the City Council sets the rates. The Florida Public Service Commission, which oversees private utilities, has no authority over rates at city-owned water systems. The only standard in state law is that a city’s water and sewer rates must be “just and equitable.” A rate study the council heard on Feb. 21, 2023, shows where the money already goes. The utility was sending about 15 percent of all the money it took in to the city’s general fund, the account that pays for police, parks and the rest of city government. After talks with city staff, the consultants recommended bringing that share down to 11 percent by the 2027 budget year, and they projected the transfers would still average about $3.1 million a year over that time. State law does not limit how high a council can set that share.
The Legislature came close to a limit this year. A Senate utility bill, as first written, capped how much of a city utility’s revenue could go to general government. A Senate committee took that cap out, and the version that became law, House Bill 1451, protects only water customers who live outside a city’s limits by cutting how much more a city may charge them. Florida TaxWatch, a taxpayer research group, has called these transfers “like a tax” and asked lawmakers to require that utility money stay with the utility.
So what stops Clermont from raising my water bill by half to cover the rest of its budget? The council would have to vote for it at a public hearing, where residents can speak. I am not saying Clermont plans to do this, and I have seen nothing that says it does. I also have not found any official estimate of how much of the Amendment 3 cut would come back to homeowners through fees. The state’s official revenue estimators counted only the property tax money local governments would lose. They did not estimate how cities and counties would make it up.
Where part of your insurance premium goes
The company named on your homeowners policy is often one of several businesses with the same owners. These sister companies run the insurer’s daily operations, handle its claims or sell its policies, and they bill the insurer for that work. The biggest is usually the managing general agent, or MGA, which is often paid a set share of every premium. If that share is 25 percent and the state approves a 20 percent rate increase on a $5,000 policy, the sister company’s cut goes from $1,250 to $1,500 for the same work. When the state’s insurance regulator, the Office of Insurance Regulation, reviews a rate request, the law has it count the insurer’s expenses, and the fee is one of them. The regulator does not have to look at what the sister company earns from that fee. These arrangements are legal and common in Florida.
In 2020 and 2021, the regulator paid a consulting firm, Risk & Regulatory Consulting, to study them. Its summary, dated March 31, 2022, looked at 2017 through 2019. The Orlando Sentinel and the South Florida Sun Sentinel added up the results, leaving out a few companies whose numbers were very different from the rest. Across those three years, the insurers reported losses of about $432 million while their sister companies made about $1.3 billion in profit. The MGA agreements took 20 to 34 percent of premium. For one insurer, all the sister companies’ fees together came to 63 percent of what that insurer collected. The newspapers’ review of 2025 filings found several major Florida insurers still paying their sister companies 20 to 35 percent of premium.
The insurers dispute the study. “The narrative that the subsidiaries and MGAs are a clever way to hide money is absolute nonsense,” Locke Burt, chief executive of Security First Insurance, told the papers. Paresh Patel, who runs HCI Group, said the consultant used an “arbitrary standard” for what counts as fair and did not apply it the same way to every company. Insurers also point out that Hurricanes Irma and Michael hit during the study years and drove up their losses. The consultant, Jan Moenck, told a House panel in 2025 that she had not judged whether the fees raised anyone’s premium.
What happened when the House tried to look
On Feb. 4, 2026, the Florida House passed House Bill 1399 by 106 votes to 3. It would have required the regulator to count the sister companies’ profits when it reviews an insurer’s rates, made those companies register with the state, and made insurers show why each payment to one of them is fair and reasonable. The Senate sent it to its Rules Committee on Feb. 9, and it died there on March 13 without a vote. A similar Senate bill, Senate Bill 234, died in its Banking and Insurance Committee. I could not find a public reason from the Senate for letting either bill die.
The consultant’s full report stayed out of public view until this month, and the Senate tried to keep it that way, as we reported Sept. 24. The Senate had sent the two Sentinel newspapers a copy with nothing blacked out, in answer to a public records request. On Sept. 15, the Senate’s general counsel, Tom Thomas, told the papers to shred it. He wrote that it contained “sensitive, proprietary trade secrets” and had been released by mistake, and the papers reported that his letter warned further use could be a felony. They published it on Sept. 19. As of this weekend, no charge against the papers had been reported. The insurance commissioner, Michael Yaworsky, has asked the Legislature to spell out what “fair and reasonable” means in dollars. The Legislature has not done so.
Who pays the premium
Amendment 3’s larger exemption goes only to homesteads, the homes their owners live in. Insurance is paid on far more than that, including rentals, condo buildings and stores. The owners of those buildings pass the cost along in rent, condo dues and prices. “Insurance costs contribute to higher building operating expenses for multifamily operators. These costs can be passed on to already struggling renters through higher rents,” the Bipartisan Policy Center, a Washington research group, wrote in a February 2025 report.
That is why I think the sister-company fees are the place to start. A tax cut on homesteads helps the people who own and live in their homes. If a closer look at those fees brought insurance rates down, that would help them too, and also the renter, the condo owner and the small business owner.
Who oversees what
DOGE could not have audited the insurers. The order that created it covers only government bodies, from state agencies down to cities. House Bill 1399 died in the Senate, which is part of the Legislature, and neither the governor nor Ingoglia’s office controls it.
Both men do help choose the insurance regulator. Florida’s insurance commissioner is appointed by the Financial Services Commission, which has four members: the governor, the attorney general, the agriculture commissioner and the chief financial officer. Ingoglia and DeSantis hold two of those four seats. Ingoglia’s office has acted against insurers in other ways. In September 2025, his office fined eight insurers a total of $2 million for not keeping promises they made after Hurricanes Ian and Idalia. I have found no public position from either man on House Bill 1399 or on the sister-company fees.
What you can do with this
Vote on Amendment 3 for your own reasons, and read what it would do to your county before you do. Check the water, sewer and other city charges on your bills after your city’s next budget hearings. When your homeowners renewal comes in, ask your agent whether the insurer uses a sister company as its MGA and what share of the premium that agreement takes. If it is a set share, that share of your increase goes to the sister company. The Legislature meets again on March 2, 2027. A bill on those fees would have to be filed again, and any legislator, House or Senate, can file one.
- Executive Office of the Governor, DeSantis and Ingoglia on local spending found by Florida DOGE audits, Oct. 1, 2025. Florida Governor.
- News4JAX on the Jacksonville airport hologram and Mayor Deegan’s response, Oct. 1, 2025. News4JAX.
- Action News Jax on the city council’s $75,000 count and the permit fund, via Yahoo News. Yahoo News.
- News4JAX on the hologram’s removal and Deegan’s statement, Feb. 4, 2026. News4JAX.
- WFTV on Orlando’s poet laureate, hot yoga classes and Mayor Dyer’s response, Oct. 7, 2025. WFTV.
- Axios Tampa Bay, “How Florida DOGE is teeing up DeSantis’ push to cut property taxes,” Oct. 7, 2025. Axios.
- Executive Order 25-44, creating Florida DOGE, Feb. 24, 2025. Florida Governor.
- The Center Square on the January 2026 DOGE report and its $1.86 billion count. The Center Square.
- The Florida Trib on the gap between DOGE’s Jacksonville claims and its itemized list, Jan. 31, 2026. The Florida Trib.
- CBS12 on DeSantis defending Amendment 3 and Palm Beach County’s response, September 2026. CBS12.
- Florida Policy Institute voter guide to Amendment 3. Florida Policy Institute.
- Florida Policy Institute, Amendment 3 ballot language summary and local fiscal impacts. Florida Policy Institute.
- City of Clermont, Water and Wastewater Revenue Sufficiency Study, presented to the City Council Feb. 21, 2023. City of Clermont.
- Florida Statutes 180.13, municipal utility rates. Florida Senate.
- Florida Senate staff analysis of SB 1724 (2026), Utility Services, including Public Service Commission jurisdiction and the removed limit on utility revenue for general government. Florida Senate.
- House Bill 1451 (2026), Utility Services, Chapter 2026-135: bill summary. Florida Senate.
- Florida TaxWatch on transferring utility profits to a city’s general fund. Florida TaxWatch.
- Orlando Sentinel and South Florida Sun Sentinel on the consultant’s findings, the 2025 filings and the insurers’ responses, Sept. 25, 2026, via InsuranceNewsNet. InsuranceNewsNet.
- Insurance Business on the Sentinels’ findings and the House vote, Sept. 2026. Insurance Business.
- Orlando Sentinel and South Florida Sun Sentinel, “How Florida fights to hide insurers’ finances,” Sept. 19, 2026, via InsuranceNewsNet. InsuranceNewsNet.
- Florida Legislature, House Bill 1399 (2026), Property Insurance Affiliates: bill history and votes. Florida Senate.
- Property Insurance Coverage Law Blog on the Senate and the affiliate bills. Property Insurance Coverage Law Blog.
- WPTV on Ingoglia’s $2 million in fines against eight insurers, Sept. 2, 2025. WPTV.
- Bipartisan Policy Center, “Rising Property Insurance Costs: Opportunities for Federal Action,” February 2025. Bipartisan Policy Center.
- Florida Statutes 196.075, additional homestead exemptions for persons 65 and older. Florida Senate.
- Sarasota County Property Appraiser, 2026 income limit for the senior exemption. Sarasota County Property Appraiser.
- Office of Insurance Regulation, organization and the Financial Services Commission. Florida OIR.